
The Kyle Busch Pacific Life Lawsuit: 2026 Settlement and the Risks of IUL Policies
In the high-speed world of NASCAR, two-time Cup Series champion Kyle Busch is known for his precision and calculated risks. However, a legal battle off the track has recently concluded with a significant, albeit confidential, resolution. As of March 2026, the Kyle Busch Pacific Life lawsuit has officially reached a settlement, ending a multi-million dollar dispute over what the racing legend termed a “misleading” and “predatory” life insurance scheme. Filed alongside his wife, Samantha Busch, the litigation centered on an Indexed Universal Life (IUL) insurance strategy that allegedly resulted in a net out-of-pocket loss exceeding $8.5 million.
For financial planners and legal experts monitoring corporate litigation in 2026, the Busch case serves as a landmark “cautionary tale” regarding the complexities of high-value insurance products. This article explores the March 2026 settlement notice, the specific allegations regarding “Project Nessie”-style mathematical projections, and the broader implications for the consumer rights and litigation update landscape in the insurance sector.
The Allegations: A “Tax-Free Retirement” That Wasn’t
The lawsuit, originally filed in October 2025 in North Carolina federal court, accused Pacific Life Insurance Company and an Arizona-based agent, Rodney Smith, of violating the North Carolina Unfair and Deceptive Trade Practices Act. The Buschs alleged that they were induced into paying more than $10.4 million in premiums for five separate IUL policies. According to the complaint, these products were marketed as “tax-free retirement plans” that would become self-sustaining after just five annual payments of $1 million each.
The “promised” outcome was alluring: once Kyle turned 52, the couple was told they could withdraw approximately $800,000 per year in tax-free income while maintaining a massive $44.5 million death benefit. However, the reality hit in early 2025 when the Buschs received a notice for a sixth $1 million premium. Upon investigating, they discovered that far from growing, the cash value of their policies was being rapidly depleted by undisclosed fees and “performance factor” charges that ranged from 3% to 7% of the total cash value annually. The lawsuit claimed that 35% of their initial payments went toward an upfront commission that was never clearly disclosed.
The March 2026 Confidential Settlement
Throughout late 2025 and early 2026, Pacific Life fought for a dismissal of the case. The insurer argued that the Buschs were “sophisticated investors” who had signed multiple disclosures acknowledging that IUL policies are not guaranteed investments. They also claimed the lawsuit was barred by a three-year statute of limitations, as the policies were initiated seven years prior. However, the court’s refusal to immediately toss the case led to an intense period of mediation.
On March 5, 2026, the parties filed a joint notice with Judge Matthew Orso in the U.S. District Court for the Western District of North Carolina. The filing stated that a “confidential settlement” had been reached, with both sides working constructively to avoid further legal proceedings. While the exact dollar amount of the settlement remains under seal, the fact that a global insurance giant settled with a high-profile athlete suggests a desire to avoid the “PR disaster” of a public trial. Under the terms of the agreement, each party will bear its own legal fees, and the case is expected to be formally dismissed by April 2026.
The IUL “Day of Reckoning” for the Industry
Industry analysts have labeled the Kyle Busch lawsuit as a “day of reckoning” for the life insurance sector. The case highlighted a systemic issue in how IUL products are illustrated. Many agents use “straight-line” projections that assume a constant positive market return, ignoring the devastating impact of flat or down years where insurance costs continue to be deducted from the principal. In Busch’s case, the policy’s cost of insurance (COI) exploded because of the massive death benefit, effectively “eating” the cash value before it could benefit from market gains.
In 2026, this case has sparked calls for “Defined Benefit Life” reform, a movement seeking to mandate annual recalibration reports for IUL holders. For those tracking SEO strategy and legal trends, the term “IUL Fraud” has seen a 400% increase in search volume following the Busch settlement, indicating that more high-net-worth individuals are beginning to audit their own “self-funding” retirement plans.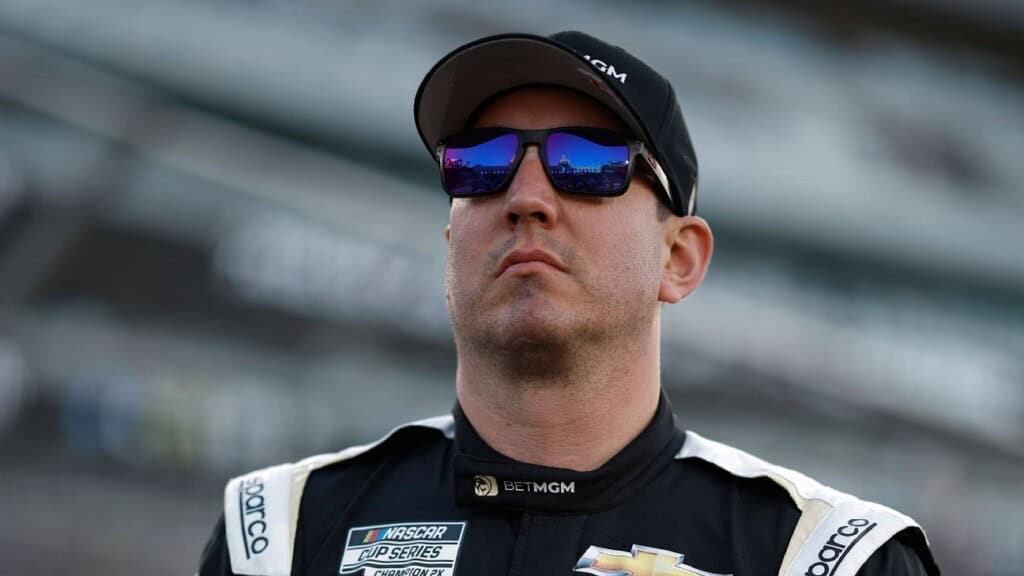
Internal Linking and Legal Guidance
The procedural hurdles faced by the Buschs—specifically the “willful blindness” defense used by Pacific Life—mirror the challenges seen in other major 2026 cases. If you are interested in how other corporations handle allegations of data and record-keeping failures, see our analysis of the Bank of America mortgage lawsuit. Similarly, the complexities of “duty of fair representation” are explored in our post on the Southwest Airlines Bianca Hughley case.
For those monitoring transparency in public expenditures, our guide on the New Mexico IPRA lawsuit offers valuable insight. You may also find our 2026 update on the Amazon antitrust trial useful for understanding broader market manipulation claims. If you believe you have been a victim of insurance misrepresentation or need a confidential consultation, please visit the Bill Jones Law Contact page. Our team also provides a full 2026 breakdown of TurboTax settlement payments for those seeking consumer restitution.